What Is the 50/30/20 Rule?
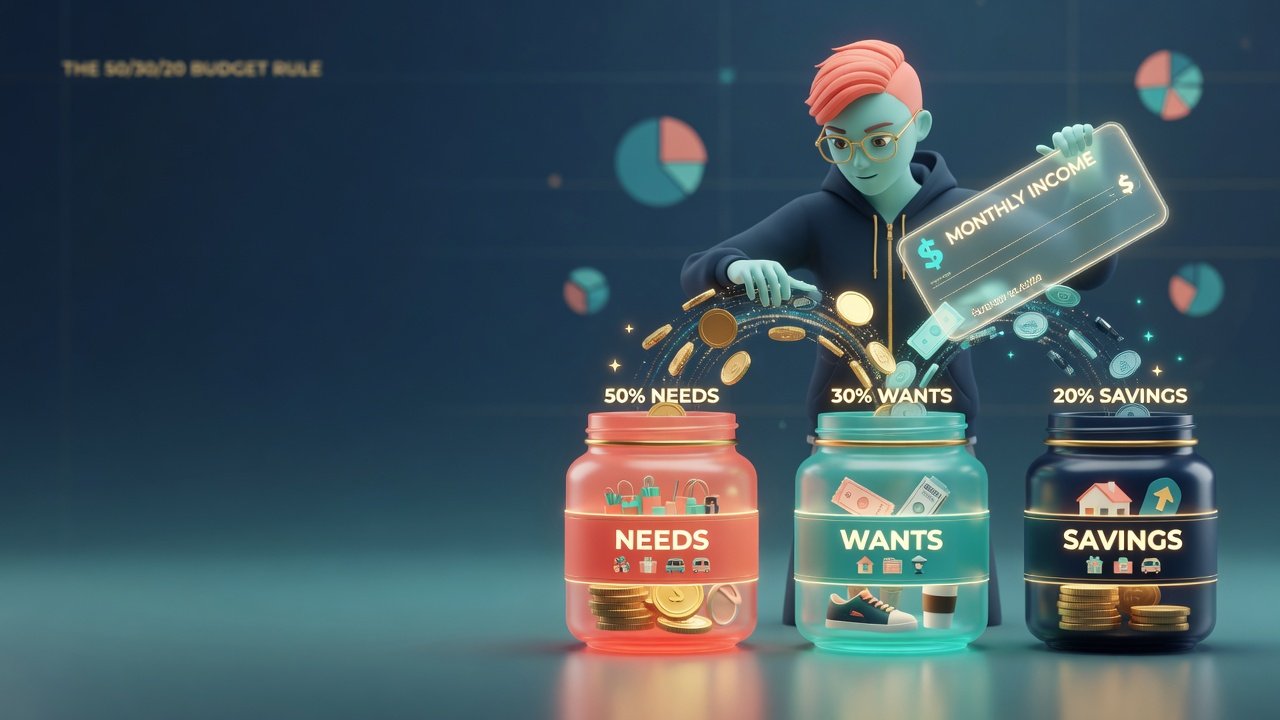
The 50/30/20 rule, popularized by Senator Elizabeth Warren in her book "All Your Worth: The Ultimate Lifetime Money Plan," is a simple budgeting framework. It divides your after-tax income into three categories: 50% for needs, 30% for wants, and 20% for savings and debt repayment.
The beauty of the rule is its simplicity. You do not need to track every coffee or categorize every transaction. You just need to know your after-tax income and ensure your spending falls roughly within these three buckets.
Needs (50%)
Needs are expenses you cannot avoid — the essentials for survival and basic functioning. These include housing (rent or mortgage), utilities, groceries, transportation, insurance, minimum debt payments, and basic healthcare.
If your needs exceed 50% of after-tax income, you are in a financially precarious position. This is common in high-cost-of-living areas or for people with low income relative to housing costs. The solution is to increase income, reduce housing costs, or both.
Housing Rule of Thumb
Housing (including utilities) should ideally stay under 30% of after-tax income. If housing alone consumes 40%+, your needs bucket will easily exceed 50%, leaving little for wants or savings.
Wants (30%)
Wants are non-essential expenses that make life enjoyable — dining out, entertainment, travel, hobbies, subscriptions, gym memberships, and non-essential shopping. These are the expenses you could cut if needed without losing basic functionality.
The 30% allocation for wants is what makes this rule sustainable. Unlike extreme frugality approaches, the 50/30/20 rule explicitly budgets for enjoyment. This prevents the burnout that often derails strict budgeting attempts.
- Dining out and takeout
- Streaming services and entertainment
- Travel and vacations
- Hobbies and recreational activities
- Non-essential clothing and shopping
- Gym memberships and wellness expenses
Savings (20%)
The 20% savings bucket includes retirement contributions, emergency fund building, investments, and extra debt payments above minimums. This is the category that builds long-term wealth and financial security.
If you are carrying high-interest debt (credit cards, personal loans), prioritize paying it off within this 20% bucket before investing. The guaranteed return of paying off 22% APR debt beats any investment return.
Example Budget
On a $75,000 salary with an effective tax rate of 20%, your after-tax income is about $5,000/month. Under the 50/30/20 rule: $2,500 for needs, $1,500 for wants, and $1,000 for savings.
That $1,000/month in savings, invested at 8% over 30 years, grows to approximately $1.49 million. The 50/30/20 rule, followed consistently, is enough to build substantial wealth over a career.
A budget is telling your money where to go instead of wondering where it went. The 50/30/20 rule makes this simple enough to actually follow.
When the Rule Does Not Fit
The 50/30/20 rule is a guideline, not a law. In high-cost cities, needs may consume 60-70% of income, making the rule unrealistic. In that case, focus on increasing income or relocating rather than forcing an impossible budget.
Conversely, if you earn significantly above average or live in a low-cost area, you might flip the ratio — living on 30% needs, 20% wants, and 50% savings. This is the approach many FIRE movement followers take.
Put It Into Practice
Use our Budget Calculator to automatically split your income into the 50/30/20 categories. Enter your after-tax monthly income and see exactly how much you should allocate to each bucket.
Pair it with the Savings Goal Calculator to set specific targets within your 20% savings bucket, and the Net Worth Calculator to track your progress over time.