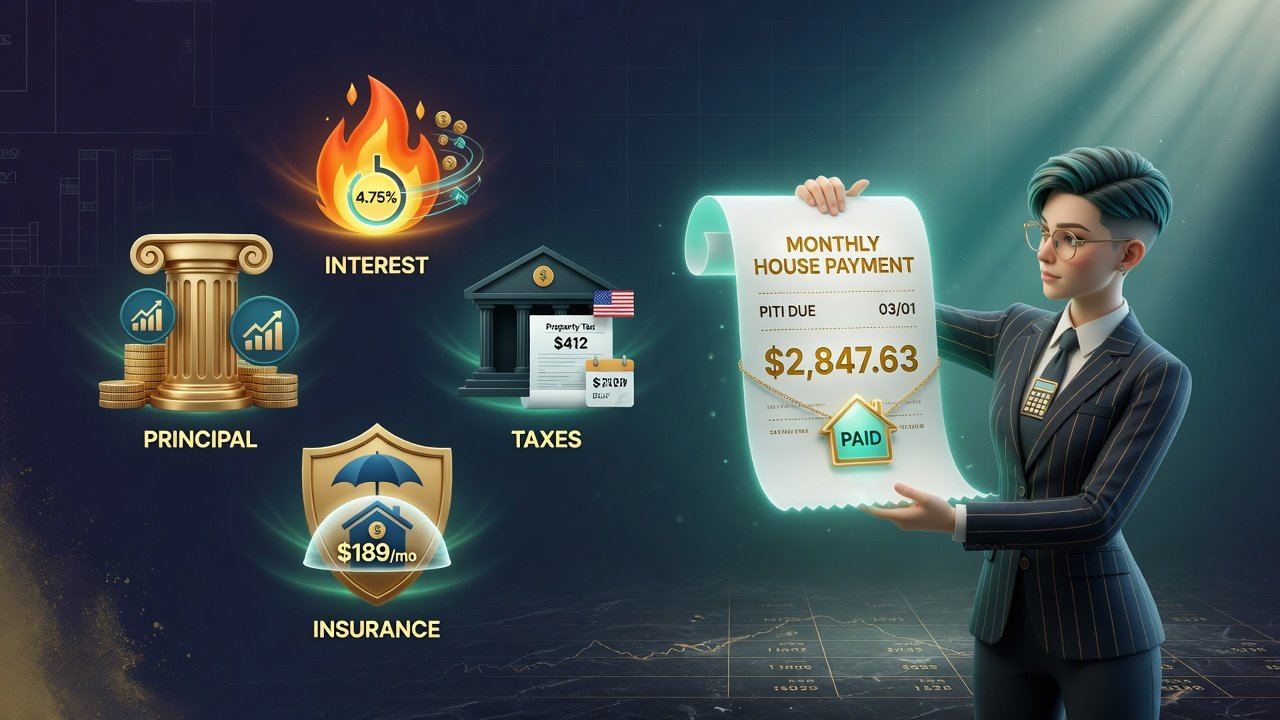
What Is PITI?
PITI stands for Principal, Interest, Taxes, and Insurance — the four components that make up your true monthly mortgage payment. Most online calculators only show principal and interest (P&I), but your actual payment to the lender is typically higher because property taxes and insurance are collected through an escrow account.
Understanding PITI is critical for budgeting. If you only calculate P&I, you may underestimate your housing cost by 20-40%.
Principal
Principal is the portion of your payment that goes toward reducing your loan balance. In the early years of a mortgage, principal is a small fraction of your payment — most of it goes to interest. Over time, as the balance decreases, more of each payment goes to principal.
This is called amortization. On a 30-year fixed mortgage, you pay mostly interest for the first 10-15 years. The principal portion grows gradually until the final years, where almost the entire payment is principal.
Interest
Interest is the cost of borrowing the principal. It is calculated each month based on your outstanding loan balance and your annual interest rate divided by 12. In the first month of a $400,000 loan at 7%, you pay $2,333 in interest alone.
Your interest rate is determined by market conditions, your credit score, your down payment, and the loan term. A 1% difference in rate on a $400,000 loan over 30 years means $95,000 more in total interest paid.
Rate Impact Example
On a $400,000 30-year loan: at 6.5% your P&I is $2,528/month. At 7.5% it is $2,797/month. That 1% difference costs $269/month or $96,840 over the full term.
Property Taxes
Property taxes are assessed by your local government and vary widely by location. The national average is about 1.1% of home value per year, but rates range from 0.3% in Hawaii to 2.5% in parts of New Jersey and Texas.
On a $400,000 home at 1.2%, your annual property tax is $4,800 — or $400/month added to your PITI. Most lenders collect this through an escrow account, spreading the annual bill across 12 monthly payments.
Insurance
Homeowners insurance protects against damage to your property and liability claims. The national average is about $1,500-$2,500 per year depending on location, home value, and coverage level.
If you put less than 20% down on a conventional loan, you will also pay Private Mortgage Insurance (PMI), typically 0.5-1.5% of the loan amount annually. PMI is separate from PITI but is added to your monthly payment.
- Homeowners insurance: $150-$250/month on average
- PMI (if under 20% equity): $125-$375/month on a $300,000 loan
- FHA mortgage insurance: upfront + annual premium
- HOA dues (if applicable): not part of PITI but part of housing cost
Calculating Your Full PITI
On a $400,000 home with 10% down ($360,000 loan) at 7% for 30 years: P&I is $2,395. Property taxes at 1.2% ($400/month). Insurance at $175/month. Total PITI: $2,970/month.
That is 24% more than the P&I alone. If you also have PMI at 0.5% ($150/month), your total housing payment is $3,120 — 30% higher than what a basic calculator shows.
The 28/36 Rule
Lenders typically follow the 28/36 rule: your PITI should not exceed 28% of your gross monthly income, and your total monthly debt (including PITI, car loans, student loans, credit cards) should not exceed 36%.
On a $100,000 salary ($8,333/month gross), your maximum PITI under the 28% rule is $2,333. With a 10% down payment and 7% rate, that supports a home priced around $320,000-$350,000 depending on taxes and insurance.
Always calculate PITI, not just P&I. The difference can be hundreds of dollars per month — enough to make a home unaffordable even when the price looks right.
Put It Into Practice
Use our Mortgage Calculator (PITI) to get your true monthly payment including taxes and insurance. Adjust the down payment, rate, and home price to find what fits your budget.
The calculator includes a full amortization schedule so you can see exactly how much principal and interest you pay each month over the life of the loan.